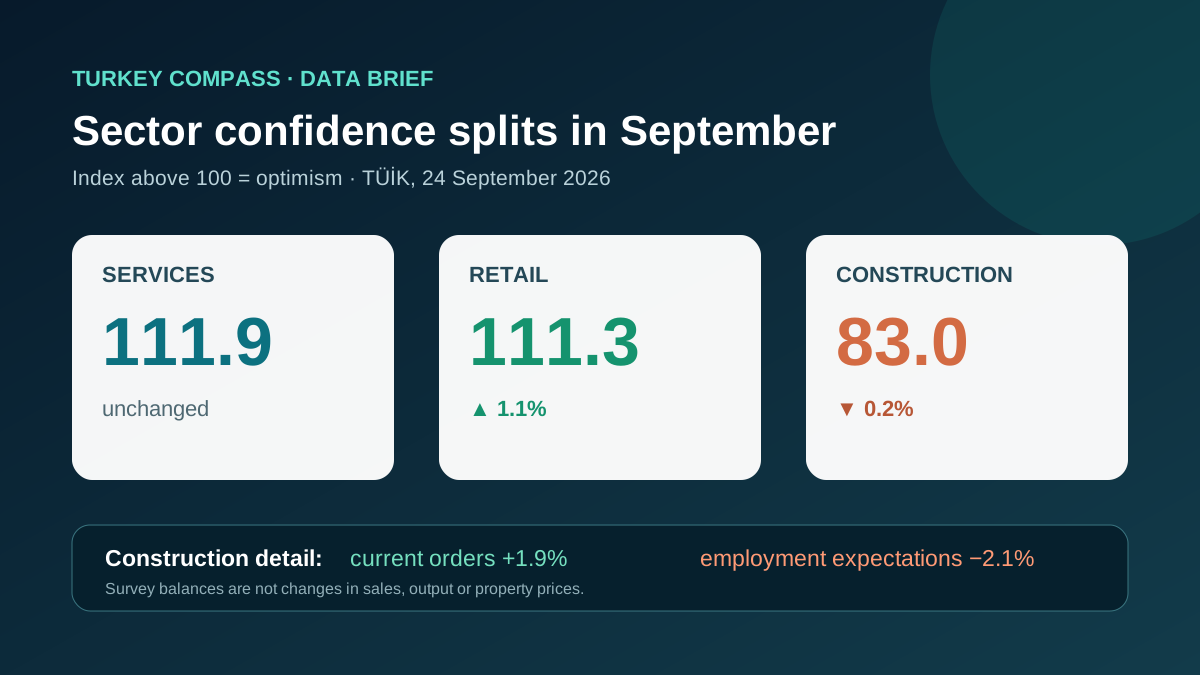
Turkey's September confidence survey showed a sharper divide between consumer-facing trade and construction. TÜİK reported on 24 September 2026 that retail confidence rose 1.1% to 111.3, services held at 111.9 and construction eased 0.2% to 83.0. Values above 100 indicate optimism and values below 100 pessimism, but these are survey balances rather than changes in revenue, output or property prices.
Retail expectations drove the improvement
Retailers' expectation for sales over the next three months rose 3.5% to 128.0, while their assessment of sales over the past three months increased 0.4% to 114.5. The stock indicator fell 1.3% to 91.4; under TÜİK's construction of this component, a lower reading means respondents reported more stock. Investors should therefore test whether stronger sales expectations are supported by turnover, margins and inventory discipline.
Services were stable, but forward demand softened
The services headline stayed at 111.9. The assessment of the recent business situation rose 1.1% to 110.2 and recent demand increased 0.4% to 109.7. Demand expectations for the next three months, however, fell 1.3% to 115.9. That mix suggests current resilience with a less confident forward view, not an across-the-board acceleration.
Construction orders improved despite a weak headline
Construction confidence slipped 0.2% to 83.0 and remained well below the neutral 100 line. Current registered orders rose 1.9% to 80.4, while employment expectations for the next three months fell 2.1% to 85.5. For a buyer or investor, the better order book does not cancel the caution implied by staffing plans and the sector's still-pessimistic overall balance.
What international investors should verify
Confidence indices are early signals, not due-diligence substitutes. For retailers and service businesses, check audited sales, customer mix, lease costs, inventories and foreign-exchange exposure. For a construction or property project, verify the land title, permits, progress certificates, financing, contractor obligations, presales and delivery history. A national survey cannot validate an individual company or development.
The next release matters more than one monthly move
TÜİK seasonally adjusts the series, but monthly readings can still react to temporary conditions and expectations. September reversed part of August's retail decline, while construction's internal signals split between orders and hiring. The next sector-confidence bulletin is scheduled for 26 October 2026; hard sales, permits, output and employment data should be read alongside it.