Türkiye's first national green-taxonomy regulation took effect on 24 September 2026. It establishes a classification system intended to direct finance toward environmentally sustainable activities and curb greenwashing. For international investors, lenders and companies, the immediate significance is a common framework for assessing eligible and aligned activities. It does not mean that every Turkish company must file a taxonomy report today, or that a Turkish classification is automatically equivalent to the EU Taxonomy.
The three tests for an aligned activity
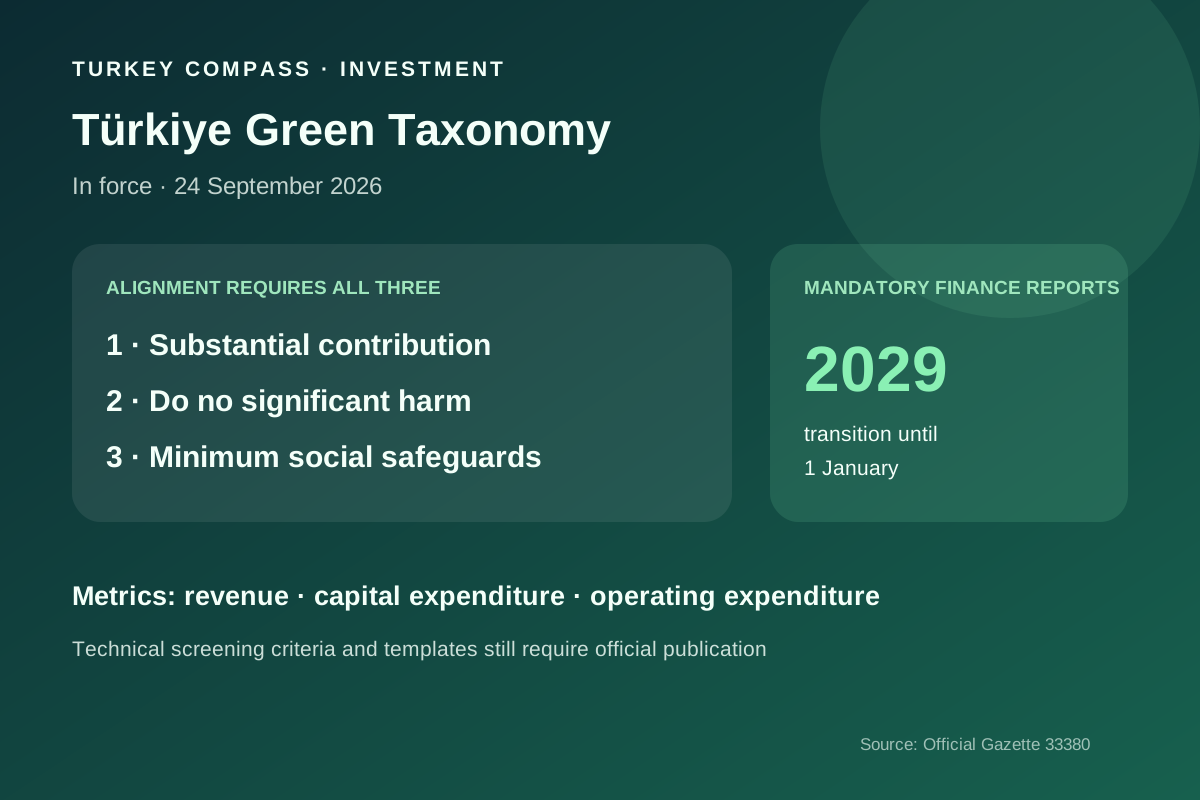
An activity listed in Annex 1 is only taxonomy-aligned when it makes a substantial contribution to at least one of six environmental objectives, does no significant harm to the others and observes minimum social safeguards. The objectives cover climate mitigation, climate adaptation, water and marine resources, the circular economy, pollution prevention and biodiversity. A business label, renewable-energy claim or ESG policy by itself does not establish alignment.
Who reports now — and who waits
Institutions and companies conducting at least one Annex 1 activity may report using templates to be published by the Climate Change Directorate. Banks, brokerages, investment and portfolio companies, insurers, reinsurers and pension companies are designated as mandatory reporters, but the transitional article says they are not required to report until 1 January 2029. Their detailed procedures will be set separately by the relevant financial regulators.
Revenue, capital expenditure and operating expenditure matter
The framework measures the shares of revenue, capital expenditure and operating expenditure connected with taxonomy-eligible or aligned products and services. A voluntary corporate reporter may leave an eligible activity out of a particular key-performance indicator when that activity represents less than 10% of the corresponding company total. Financial institutions have separate indicators and may request taxonomy reporting from companies whose data they need.
Important technical rules are still to come
The regulation establishes the architecture, but the Climate Change Directorate must publish the technical screening criteria, reporting templates, transition-plan rules and verification procedures. Updated criteria are to be published by 15 December and take effect in the following year. Solid-fossil-fuel production activities cannot be treated as environmentally sustainable. Investors should therefore avoid treating the framework alone as a ready-made green-asset certificate.
What international investors should check
For a Turkish project, fund or acquisition, identify the exact Annex 1 activity, the reporting entity and the relevant revenue, capital-expenditure and operating-expenditure data. Ask for the applicable screening criteria and verification basis rather than relying on a marketing statement. If an EU mandate, bond framework or foreign disclosure rule applies, test it separately: the Turkish regulation does not declare automatic legal equivalence with another jurisdiction's taxonomy.
Turkey Compass fact check
Confirmed: the national taxonomy regulation is in force and financial institutions are named as mandatory reporters. Also confirmed: their reporting obligation is deferred until 1 January 2029. Not confirmed: that every company must report immediately, that every Annex 1 activity is automatically green, or that the regulation by itself certifies compliance with the EU Taxonomy.
Official Gazette — Annex 1 to the Türkiye Green Taxonomy Regulation, 24 September 2026 →